Disclosed, Then Closed: Challenging a Bank Exit After a Vulnerability Disclosure
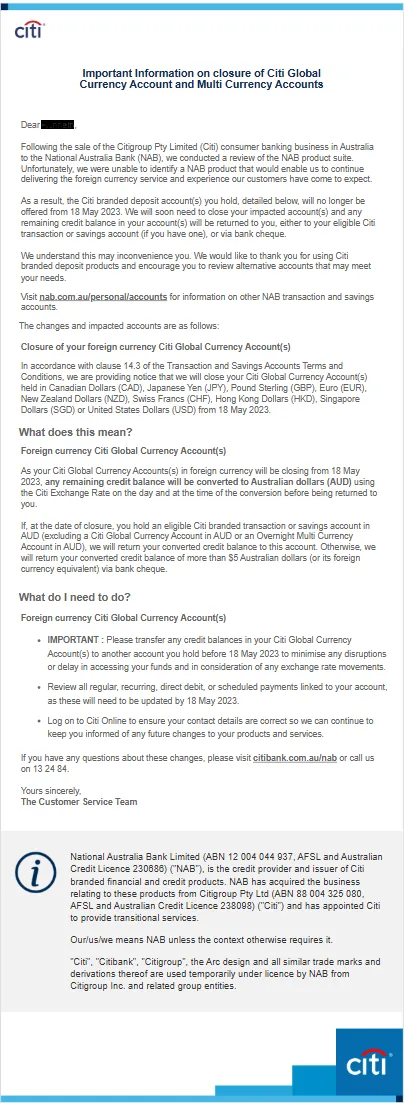
Photo: Travelweb.au, CC BY-SA 4.0, via Wikimedia Commons
A bank’s vulnerability question is usually framed as an offer of help: tell us if you are going through something difficult, and we can adjust how we communicate, how we process payments or how we handle debt. For most customers, that is exactly what happens. For a minority, the sequence runs differently. They disclose a mental health condition, a gambling addiction or coercive control at home, and within weeks a closure letter arrives. The disclosure may not be the stated reason, but the timing is difficult to ignore. The question for this article is not whether banks may ever close accounts held by vulnerable customers — they can — but whether a closure that follows a disclosure has been reached fairly, and how a customer can test that decision.
What the rules require — and what they do not
The starting point is the Financial Conduct Authority’s Consumer Duty, which requires firms to act to deliver good outcomes for retail customers and to pay particular regard to those in vulnerable circumstances. The FCA’s vulnerability guidance, FG21/1, is more specific: firms should recognise vulnerability, take reasonable steps to understand it, and avoid causing additional harm. The Equality Act 2010 also matters where a mental health condition amounts to a disability. It creates a duty to make reasonable adjustments and prohibits discrimination arising from disability.
None of this creates an absolute right to a bank account. A bank can still close an account in line with its terms, provided it gives proper notice and treats the customer fairly. Vulnerability does not shield a customer from a genuine fraud investigation, nor does it prevent a bank from acting on repeated unauthorised overdrafts or a court order. The regulatory question is whether the bank took vulnerability into account at the point of decision, or whether it used a broad risk label to avoid engaging with the customer’s circumstances.
When ‘risk appetite’ stands in for a reason
Closure letters are often cautious. They may refer to a ‘commercial decision’, a ‘review of the relationship’ or the bank’s ‘risk appetite’. Those phrases are not, by themselves, unlawful. Banks are entitled to set risk parameters. But a vague reference to risk appetite becomes harder to defend when the customer has just disclosed a condition that may affect their behaviour, memory, communication or exposure to financial abuse.
There are several patterns that should prompt scrutiny. A customer with a long, clean account history discloses a mental health crisis and is then exited without any transaction-level concern being identified. A customer discloses coercive control and the bank closes the account rather than discussing safeguards such as a trusted contact, spending controls or a safer communication channel. A customer with a gambling addiction is exited after a burst of gambling transactions, without any attempt to apply blocks, cooling-off periods or signposting to specialist support. In each case, the bank may say it was managing risk. The customer may reasonably ask whether the bank managed the vulnerability or simply removed the customer.
Building the paper trail
The first practical step is to obtain the record. A subject access request under the UK GDPR is free and should be answered within one month, although complex requests can take longer. Ask specifically for closure decision records, internal risk assessments, call notes, vulnerability flags and any correspondence between teams about the account. If the bank withholds some material, ask for the gist of it. A subject access request will not necessarily produce a detailed explanation, but it often reveals whether a vulnerability disclosure was recorded and whether anyone considered it before the decision was made.
Put the request in writing and keep a chronology. Record the date of the disclosure, who received it, what was said, and what changed afterwards. Avoid relying on recollections of telephone calls. If a call handler promised support or said the disclosure would not affect the account, note the date, time and any reference number. This chronology will form the backbone of any complaint.
Complaint first, Ombudsman second
A formal complaint should do more than express frustration. It should identify the disclosure, the decision, and the gap between them. Reference the Consumer Duty and FG21/1 where relevant. If the customer has a disability within the meaning of the Equality Act 2010, say so and ask what reasonable adjustments were considered. Request reinstatement if that is realistically wanted, or a clear written explanation and compensation for distress and inconvenience if it is not.
The bank has eight weeks to respond. If it does not resolve the complaint, or if the response is unsatisfactory, the Financial Ombudsman Service can consider the matter. There is a six-month deadline from the bank’s final response, so do not let the complaint drift. The Ombudsman decides what is fair and reasonable in the circumstances, which gives it scope to look beyond strict contractual terms.
Framing the Ombudsman referral
The strongest referrals are specific. Rather than saying only ‘I want my account back’, explain that the bank failed to take account of a disclosed vulnerability, applied a blanket risk policy, and did not consider adjustments that would have allowed the relationship to continue. Attach the closure letter, the complaint correspondence, any evidence of the disclosure and, if the customer is comfortable, medical or specialist evidence. Explain the practical impact: lost salary payments, damaged credit, difficulty paying bills, or the distress of managing a household without a bank account.
Be realistic about remedies. The Ombudsman can award compensation and require the bank to review its decision, but it cannot force a bank to maintain a relationship that has broken down. Reinstatement is possible but not guaranteed. A well-framed referral is still worthwhile: it tests the bank’s reasoning, may produce a financial remedy, and can lead to a correction on the customer’s record.
What to do alongside the complaint
Do not wait for the complaint to conclude before securing alternative banking. A basic bank account, a second current account or a payment account with a different provider can keep income and essential bills moving. Check the credit file for any inaccurate default or closure marker. If coercive control is part of the picture, specialist domestic abuse services can advise on safe communication and financial separation. For addiction-related debt, StepChange and MoneyHelper offer free guidance.
Vulnerability should change how a bank behaves, not whether it is willing to engage at all. A disclosure is evidence of need, not an admission of unsuitability. Where a bank has treated it as the latter, a structured complaint and a carefully framed Ombudsman referral are the proper ways to test that decision.