When the Bank Says No to the Committee: A Treasurer's Action Plan for Charity Account Closures
A bank account is rarely the first thing a committee thinks about. The hall roof, the season's fixtures, the raffle licence and the grant return usually come first. But when a bank decides to close a charity, club or community group account, the paperwork becomes urgent very quickly. The organisation still has bills, insurers, utility suppliers and donors, yet the account that connects them is being switched off.
The closure may be prompted by a change of signatories, irregular cash banking, a new treasurer, a grant from overseas, or a risk rating applied to the sector rather than the group. Whatever the trigger, treasurers need a plan that protects the group's money and its ability to operate while a challenge is considered.
Separate a closure from a restriction
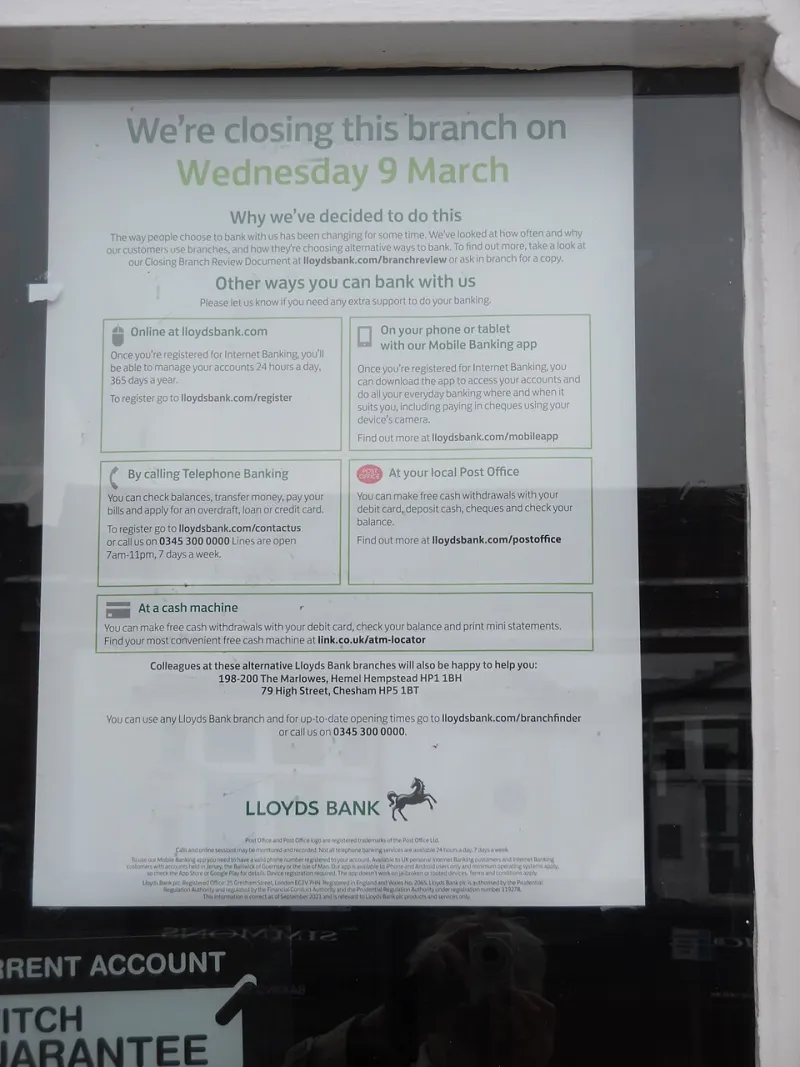
Read the notice carefully. A bank may be closing the account on a set date, or it may have restricted transactions while it reviews information. The two require different responses. Note the date of the letter, the stated reason, any deadline for appeal and whether cards, direct debits or online banking have already stopped.
Tell the committee promptly and keep a written record. Do not move funds in a way that breaches the mandate or bypasses dual authorisation. If the account is frozen, ask the bank what evidence it needs and whether essential payments, such as payroll or insurance, can be released. Keep copies of every letter, secure message and call note.
Why committee accounts attract scrutiny
Community accounts are not personal accounts with a different name. They carry a mandate, trustees or officers, and a governing document. Banks must satisfy themselves about who controls the money and what the account is for. Common problems include an out-of-date mandate after a committee election, missing identification for a new signatory, inconsistent use of the group's name, and fundraising income that does not match the account's stated purpose.
Cash-heavy activity is a particular pressure point. Summer fetes, quiz nights, bucket collections and membership subscriptions produce cash that must be banked regularly and recorded clearly. A group that banks takings in one lump sum after months of storage, or that mixes petty cash with members' money, can look riskier than it is. Overseas donations, payments to international causes or a sudden change in transaction patterns can also prompt questions.
Some closures reflect a bank's appetite for risk rather than any failing by the committee. Small charities and unincorporated associations are often costly to administer and may be judged against a broad risk framework. That does not make the closure fair, but it helps treasurers understand what they are dealing with.
Build a controlled wind-down during the notice period
Assume the closure date is real and work backwards. Convene the trustees or committee and minute the decisions. Produce a complete map of money coming in and going out: standing orders, direct debits, payroll, grant payments, Gift Aid claims, card terminal settlements, online donation platforms and cheques. Contact each payee and payer before the account stops working.
Open a replacement account as early as possible. This is often the slowest step, especially for charities and clubs that need a mandate, trustee identification and evidence of the governing document. Ask the new provider what it needs for a community group account and whether it can accept a resolution from the committee. Do not use a personal account as a temporary home for group funds; it blurs ownership and creates avoidable risk.
Protect income. Tell regular donors, grant funders and event sponsors about the new account details through a verified channel. Update Gift Aid records with HMRC where necessary and check whether the charity regulator needs to be informed of a change in financial details. Keep a clear audit trail of the transition so the annual accounts can explain what happened.
Get the mandate and signatory paperwork right
A high proportion of committee account problems begin with the mandate. When officers change, the bank needs evidence that the new treasurer or chair has been properly appointed. That usually means a minuted resolution, certified identification and an updated list of authorised signatories. The governing document may specify how many signatories are needed or which officers must approve payments.
If the group is an unincorporated association, the committee should also check its constitution and insurance position. Trustees can carry personal liability in some circumstances, so decisions about closing or moving accounts should be recorded properly.
Challenge the decision without stalling operations
Ask the bank for its reasons in writing and use its formal complaints procedure. Keep the complaint factual: what the group does, how it handles cash, who the signatories are and what evidence is available. Offer to provide the governing document, recent accounts, a cash-handling policy and minutes appointing officers. Do not ask the bank to ignore its controls; ask it to review the decision on accurate information.
If the complaint is not resolved, the Financial Ombudsman Service may be able to consider it. Many small charities and clubs fall within its eligibility rules, but the limits depend on income, employee numbers and the type of complainant, so check before assuming. Keep to the time limits set out in the bank's final response.
A challenge can run alongside the wind-down. It should not be the only plan. Banks do reverse decisions, but treasurers cannot leave insurance unpaid or a grant unclaimed while waiting.
Keep the group visible and accountable
Members and donors are more understanding when they know what is happening. Explain the closure in neutral terms, give the new account details through a trusted channel and keep minutes of decisions. After the account closes, reconcile the final statement, retain records for the required period and update the annual accounts. The closure may be a banking event, but for the committee it is also a governance test. Handled carefully, it leaves the group with clean records, continuous services and a stronger case if it decides to complain.