The Closure Window: What Still Works Between a Bank’s Notice Letter and the Final Shutdown
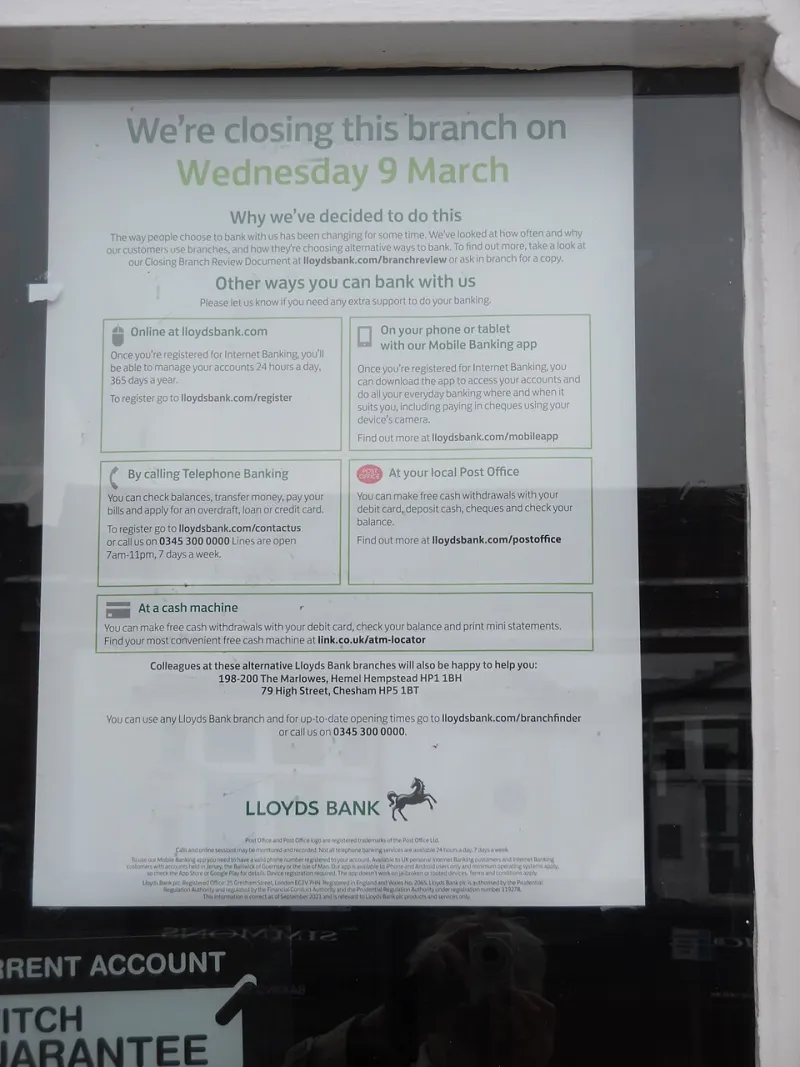
Photo: David Hillas , CC BY-SA 2.0, via Wikimedia Commons
A letter telling you that your bank intends to close your account can read like an ending. In practice, it is often a scheduled withdrawal: a date is set, a period of notice begins, and the account continues to operate in a limited, run-off state until the final shutdown. The distinction matters. Customers who treat the notice as an immediate freeze may abandon arrangements that are still functioning; customers who treat it as an indefinite grace period may leave vital payments exposed.
Notice Is Not the Same as a Freeze
UK banks use different language for different actions. A closure notice normally states that the bank will close the account on a future date and may invite the customer to make alternative arrangements. An immediate freeze, by contrast, is typically a restriction applied now, often without the same notice, and may be linked to fraud or financial crime concerns. The two can overlap, but they should not be assumed to be the same.
Read the letter for three things: the stated closure date, the reason given (or the fact that no reason is given), and any specific restrictions already in place. If the letter says the account will close on a date, ask the bank in writing whether the account remains open for day-to-day transactions until then. The answer forms the basis of your timetable.
What Usually Continues While the Account Is in Run-Off
While an account remains open, many ordinary functions continue. That is not a guarantee, and the bank’s terms and the reason for closure can change the picture, but customers should establish the position rather than assume the worst.
Cards and cash access
Debit cards often continue to work until the closure date, subject to the bank’s restrictions. Some banks block new spending but allow balance withdrawal; others allow both. Check whether contactless, online and ATM transactions are still permitted, and whether the card will be cancelled before the account closes.
Direct debits and standing orders
Existing direct debits and standing orders may continue to be paid while the account is open, provided funds are available. The risk is timing: a direct debit due after the closure date will fail unless it is moved. List every regular payment, including those you might overlook, such as subscriptions, insurance premiums and charitable donations.
Incoming salary and other credits
Incoming payments can usually still be credited while the account is open. Salary is the priority. Tell your employer’s payroll team early and ask what evidence they need. A new account’s sort code and account number should be supplied in writing, and you should confirm the date from which payroll will use them. Do not assume a payment made near the closure date will arrive safely.
Overdrafts and borrowing
An overdraft is a debt, not a feature that disappears with the account. If you have an overdraft, the bank may expect repayment on or before closure, and it may restrict further borrowing during the notice period. Check whether the overdraft remains available, whether interest and fees continue, and how the bank expects the balance to be cleared. If you cannot clear it, ask for a repayment arrangement in writing before the closure date.
Building a Migration Timetable
A closure notice is best handled as a project with dates. The following sequence is a practical starting point, not a universal rule.
Week one: inventory and new account
Open a replacement account as soon as possible, if you have not already done so. Make a list of every payment in and out, including salary, benefits, pensions, bills, subscriptions and transfers. Request a copy of your recent statement if you do not have one. Notify your employer and any regular payers of the new details.
Week two: move the plumbing
Contact each direct debit and standing order provider. Some can change bank details directly; others require a new mandate. Use the Current Account Switch Service where it is available, but do not rely on it to capture every arrangement. Check that recurring card payments, such as subscriptions, are updated separately.
Week three: test and clear
Make a small test payment into the new account and confirm it arrives. Check that salary or pension credits are redirected. Move any remaining balance, but leave enough to cover payments still due from the old account. Keep a record of every instruction and confirmation.
Final days: confirm and close
Ask the bank to confirm the exact date and time the account will stop accepting transactions. Cancel any remaining standing orders and direct debits that have not been moved. Obtain a final statement. If the account is in credit, confirm how the remaining balance will be returned.
Where Notice Quietly Becomes a Restriction
A closure notice can harden without a new letter. Watch for these signals:
- Card transactions start declining while the account is still open.
- Incoming credits are returned or held.
- Direct debits fail without explanation.
- Online banking access is limited or removed.
- The bank asks you to stop using the account before the stated closure date.
If any of these occur, ask the bank to confirm in writing whether the account has moved from notice to restriction, and on what basis. Keep the original letter and any subsequent correspondence.
If the Bank Moves the Goalposts
A bank may bring forward a closure or impose restrictions sooner than expected. If that happens, put your position in writing and ask for the reason, the relevant terms, and what you are expected to do with any balance or debt. If you are dissatisfied, the bank’s formal complaints procedure is the next step; after that, the Financial Ombudsman Service may be able to consider the complaint.
The notice period is not a grace period in the sense of unlimited time. It is a window in which the account may still function, but only if you establish what remains permitted and move the essential parts of your financial life before the window closes.